
Credit News / Mortgages
VantageScore vs. FICO for Mortgages: A Reddit Credit Explainer
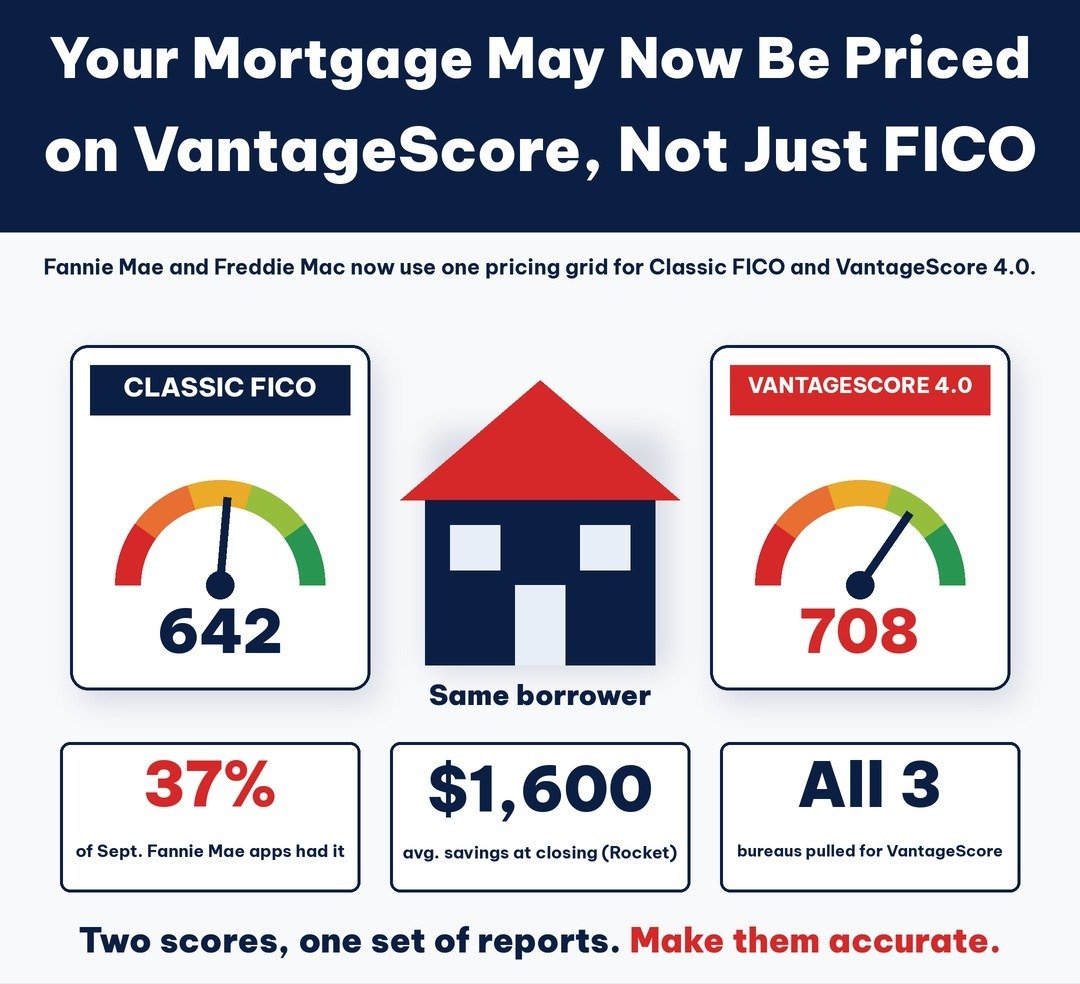
Fannie Mae and Freddie Mac now apply the same loan-level pricing to Classic FICO and VantageScore 4.0. Here is what changed, what lenders have reported, and why accurate credit reports still matter.
Credit Repair Co publishes plain-English breakdowns of credit news like changes to how mortgages use credit scores. Learn more about Credit Repair Co or explore the credit services we offer if you are working through questions on your own report.
For readers of Reddit credit communities shopping for a mortgage, this change means the score a lender uses may not be the one you’re used to seeing, and the choice can affect pricing.
What changed
Fannie Mae announced on September 30, 2026 that loan-level price adjustments are now aligned across Classic FICO and VantageScore 4.0 for loans purchased or delivered into MBS on or after October 1, 2026. HousingWire reported that FHFA Director Bill Pulte said Fannie Mae and Freddie Mac would move to one pricing grid, removing an earlier 20-point VantageScore adjustment.
Under Fannie Mae’s rules, lenders may choose Classic FICO or VantageScore 4.0, must use the same model for all borrowers on a loan, and must request VantageScore 4.0 from all three bureaus when they choose it. Manually underwritten loans still use Classic FICO.
What lenders have reported
According to Mortgage Professional America, United Wholesale Mortgage said it has seen borrowers with a 642 FICO come back with a 708 VantageScore, and Rocket Mortgage said borrowers who saved with VantageScore saved an average of $1,600 at closing.
These are company-reported examples. Your scores may move differently, or not at all, under VantageScore 4.0, and the savings figure applies only to borrowers who saved.
What this means for your credit
- Both scores come from the same reports. Errors on any of your three reports can affect either model.
- Ask your lender which model it uses. Lenders choose; you may not see the same number you check at home.
- Check all three reports. Because VantageScore 4.0 is pulled from all three bureaus, accuracy across Equifax, Experian and TransUnion matters.
The takeaway
FICO-versus-VantageScore questions are common in Reddit credit communities. The practical point: two scores, one set of reports. Keeping those reports accurate is what you can control.
Educational only. Not legal or financial advice. This article reflects reporting as of October 30, 2026; details may have changed since.
Getting ready to apply for a mortgage? Read why thousands trust us, see client reviews and results, or contact our team.
Sources: Fannie Mae, Simplified Pricing Across Credit Score Models, Sept. 30, 2026; Fannie Mae, Credit Score Models and Reports Initiative; HousingWire, FHFA one LLPA grid; Mortgage Professional America; HousingWire, Thompson questions FHFA credit score