
Credit News / Buy Now, Pay Later
Buy Now, Pay Later Is Reaching Lenders: A Reddit Credit Guide
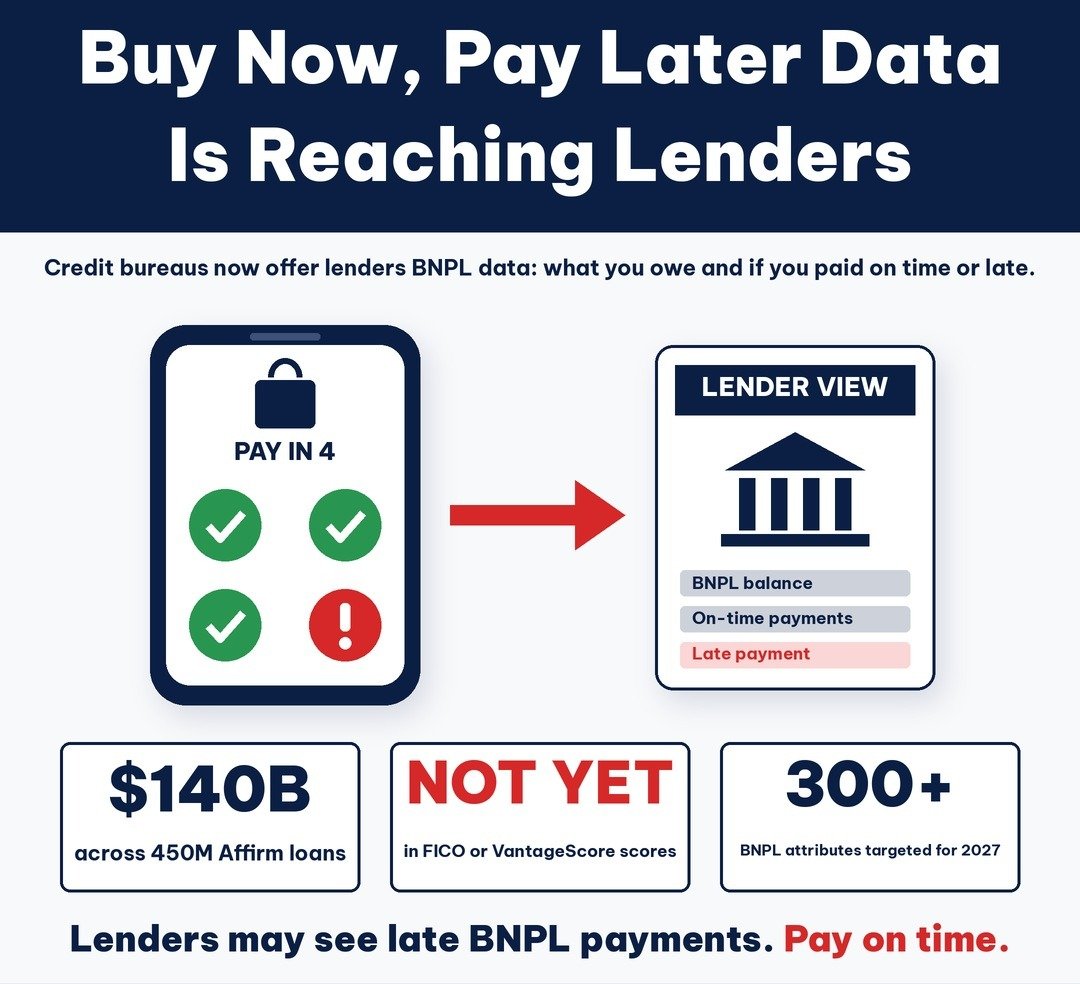
Credit bureaus have started offering lenders summarized buy now, pay later (BNPL) data, though it does not count in FICO or VantageScore scores yet. Here is what changed, and what it does not mean.
Credit Repair Co publishes plain-English breakdowns of credit news like how buy now, pay later loans show up for lenders. Learn more about Credit Repair Co or explore the credit services we offer if you are working through questions on your own report.
For readers of Reddit credit communities who use pay-in-4 or monthly BNPL plans, this is a quiet but meaningful change: lenders can now start to see how those loans are being managed.
What changed
On October 23, 2026, Affirm said the credit bureaus are now offering lenders new BNPL “attributes.” These roll a person’s BNPL loans from participating providers into one snapshot: how much they owe, how they’ve managed payments, and whether they’ve paid on time or late. The individual details stay on the consumer’s own credit report.
TransUnion says it has made a limited set of these attributes available to one lender partner so far, based on data from one BNPL furnisher. It describes the data as partial, not a complete view of anyone’s BNPL activity.
What it doesn’t mean yet
- No score change yet. Both Affirm and TransUnion say the attributes don’t currently affect FICO or VantageScore credit scores.
- Limited coverage. TransUnion’s initial release covers one lender partner and one furnisher’s data. A broader offering with more than 300 attributes is targeted for 2027, subject to product and market readiness.
- Lender choice. Lenders that choose to use the attributes may see BNPL behavior; others may not.
What this means if you use BNPL
- Late BNPL payments may become visible to some lenders. Treat BNPL due dates like any other bill.
- Check your own reports. Some BNPL providers already report payment activity, so plans can appear in your credit history. If anything is inaccurate, you can dispute it with the credit bureau.
- Watch for score changes later. FICO has announced BNPL-specific score models for use once the data is available at scale, but broad adoption hasn’t happened yet.
The takeaway
If you’ve seen BNPL questions come up in Reddit credit threads, the short answer as of late October 2026 is: lenders are starting to see summarized BNPL behavior, scores aren’t using it yet, and paying on time matters either way.
Educational only. Not legal or financial advice. This article reflects reporting as of October 26, 2026; details may have changed since.
Have questions about how loans like these appear on your credit report? Read why thousands trust us, see client reviews and results, or contact our team.
Sources: Affirm, “Paying on time should count,” Oct. 23, 2026; TransUnion, “BNPL Data in Credit Decisions,” updated Oct. 8, 2026